 ZANSHIN
Sign in
First-order Greek · ∂V/∂S
Delta: how much an option moves with the underlying
Delta is the change in an option's price for a $1 change in the underlying. A call with a delta of 0.40 gains about 40 cents when the stock rises a dollar.
The formula
d₁ = [ ln(S/K) + (r + σ²/2)·T ] / (σ√T)
d₂ = d₁ − σ√T
Δcall = N(d₁) Δput = N(d₁) − 1
Black-Scholes, European options, no dividends. S spot, K strike, T years to expiry, r the risk-free rate, σ implied volatility, N(·) the standard normal CDF and φ(·) its density.
Calls have delta between 0 and 1, puts between −1 and 0. At the money a call sits near 0.50. Deep in the money it approaches 1 and the option moves like the stock; far out of the money it approaches 0.
Three ways to read it
- Sensitivity. Dollars of option value per dollar of underlying.
- Hedge ratio. Short one call with delta 0.40 on a 100-share contract and you buy 40 shares to be flat. That is delta hedging, and it is what market makers do all day.
- A rough probability. Delta is often quoted as the odds of finishing in the money. It is close but not exact: the risk-neutral probability is N(d₂), not N(d₁).
Delta moves, and that's the whole game
Delta isn't fixed. It changes with price (that's gamma), with time (charm) and with implied volatility (vanna). A hedger who is flat now won't be flat after any of those move, so they trade again. Summed across every option dealers hold, those re-hedges are the flows Zanshin Flow tracks.
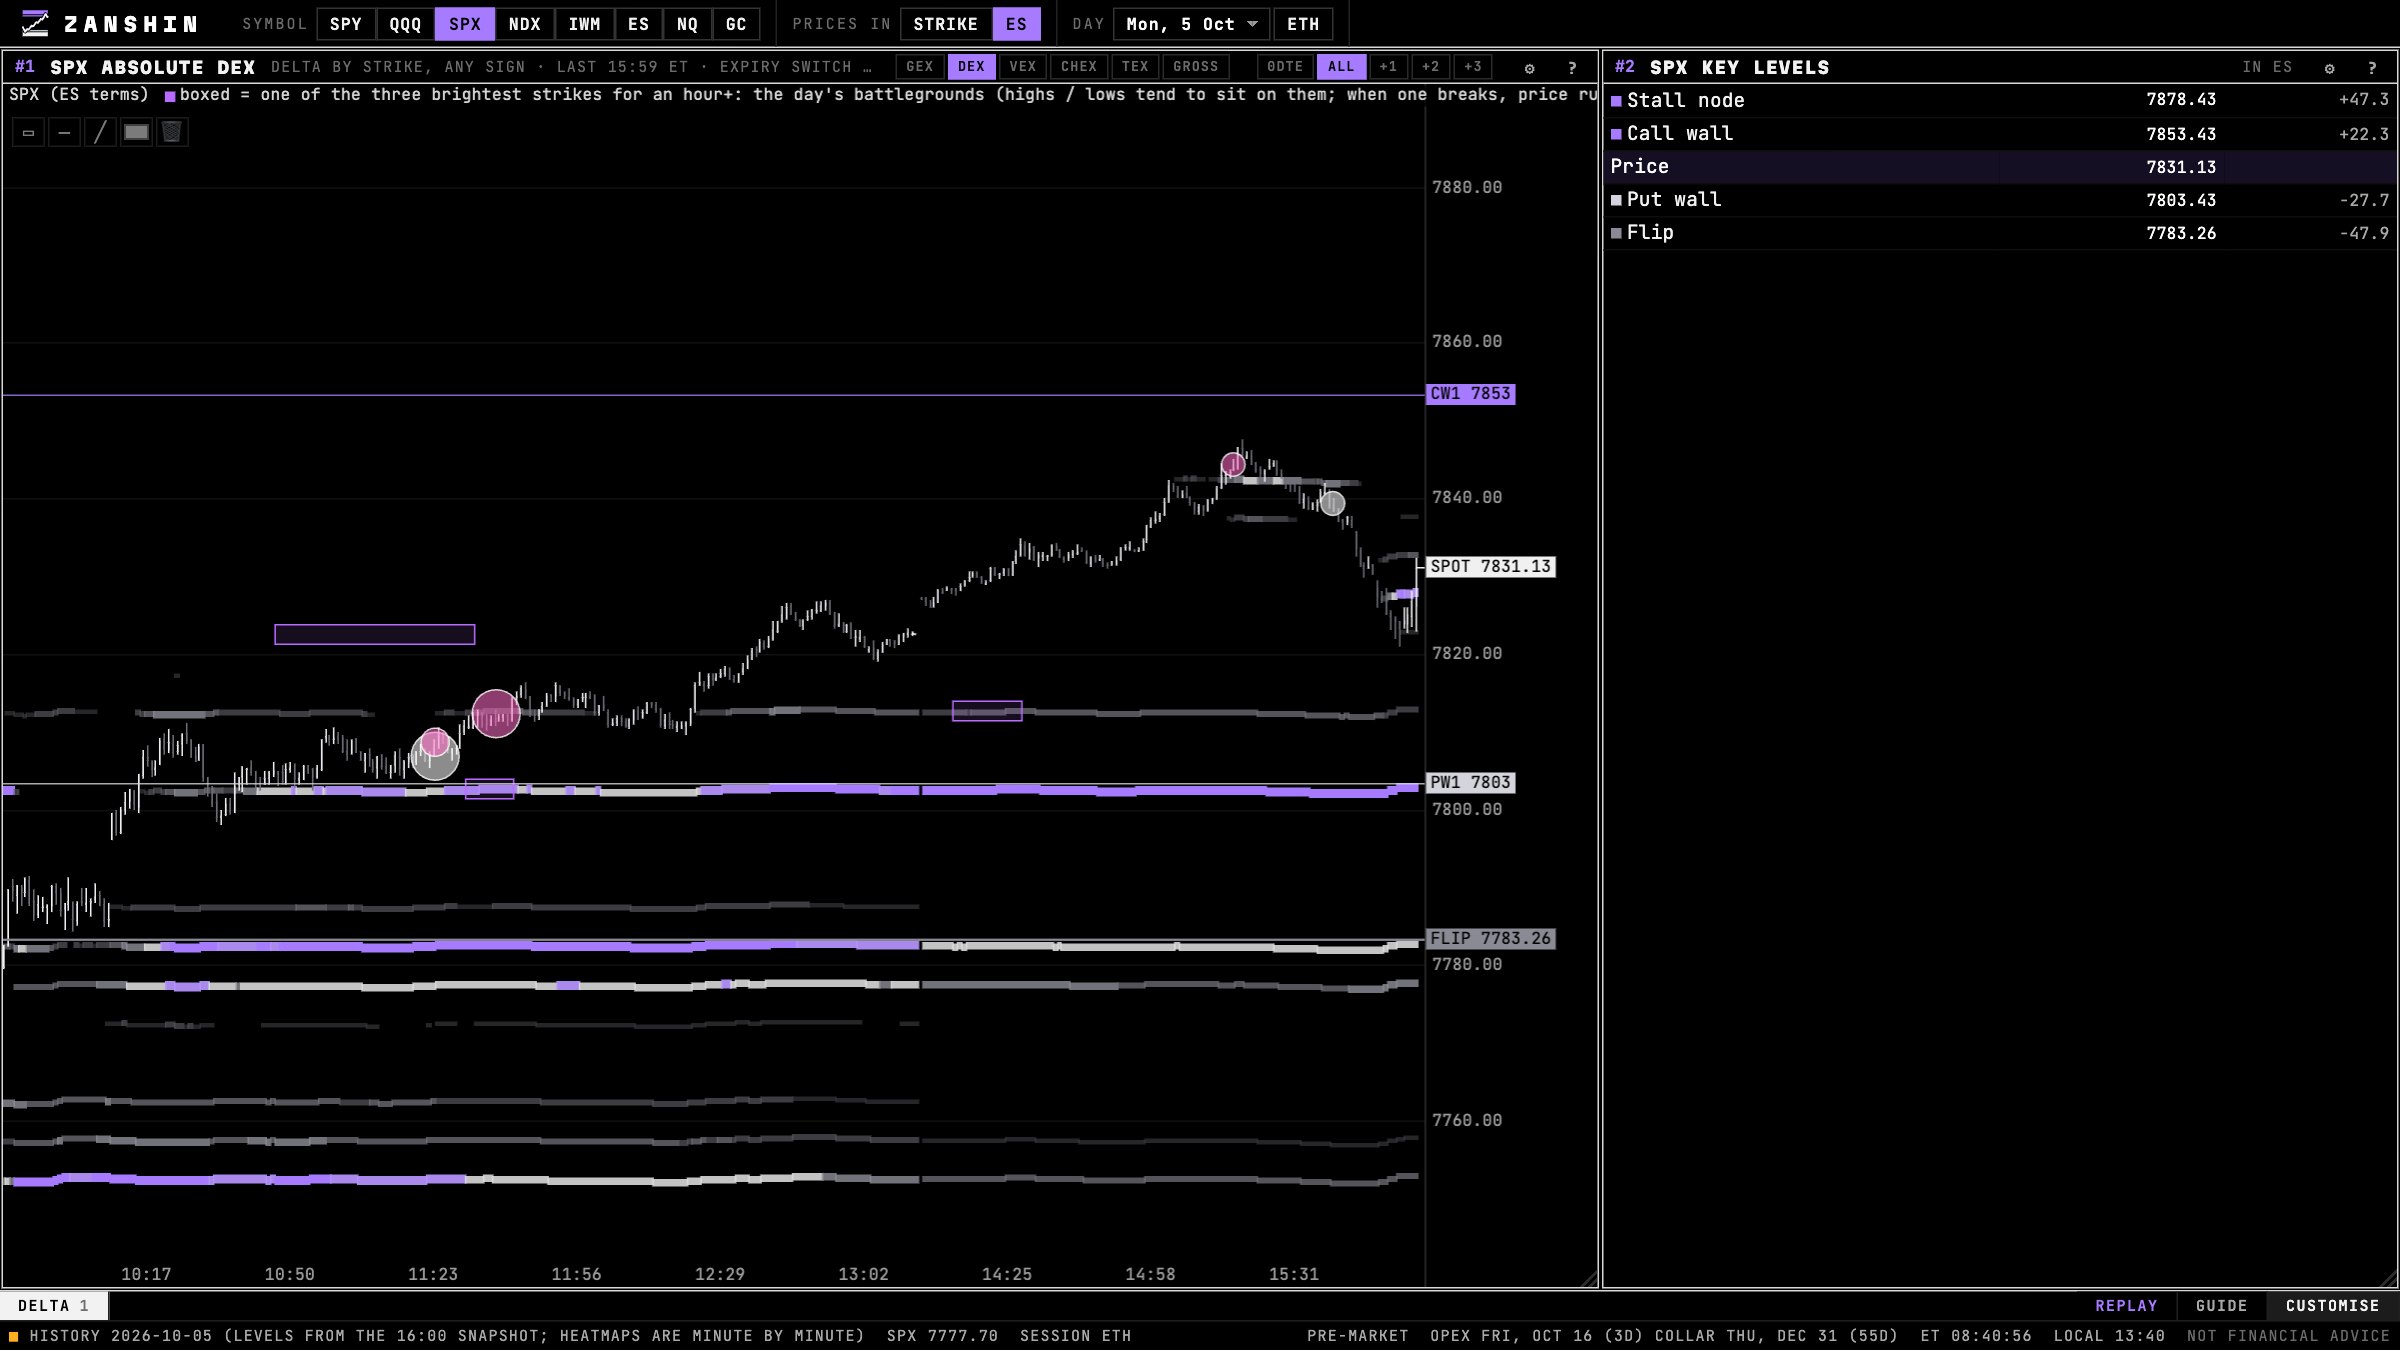
Dealer delta exposure (DEX)
Add up delta × open interest × contract multiplier across a chain, signed for the side dealers are assumed to hold, and you get dealer delta exposure: the share-equivalent position market makers carry before hedging. Zanshin Flow reports it in the Exposures window alongside gamma, vanna, charm and theta.
Questions
What does a delta of 0.50 mean?
Is delta the probability an option expires in the money?
Why is put delta negative?
Not financial advice. This article explains how options and dealer hedging work. It is not a recommendation to buy or sell anything.