 ZANSHIN
Sign in
Volatility
Expected move: the range options are pricing
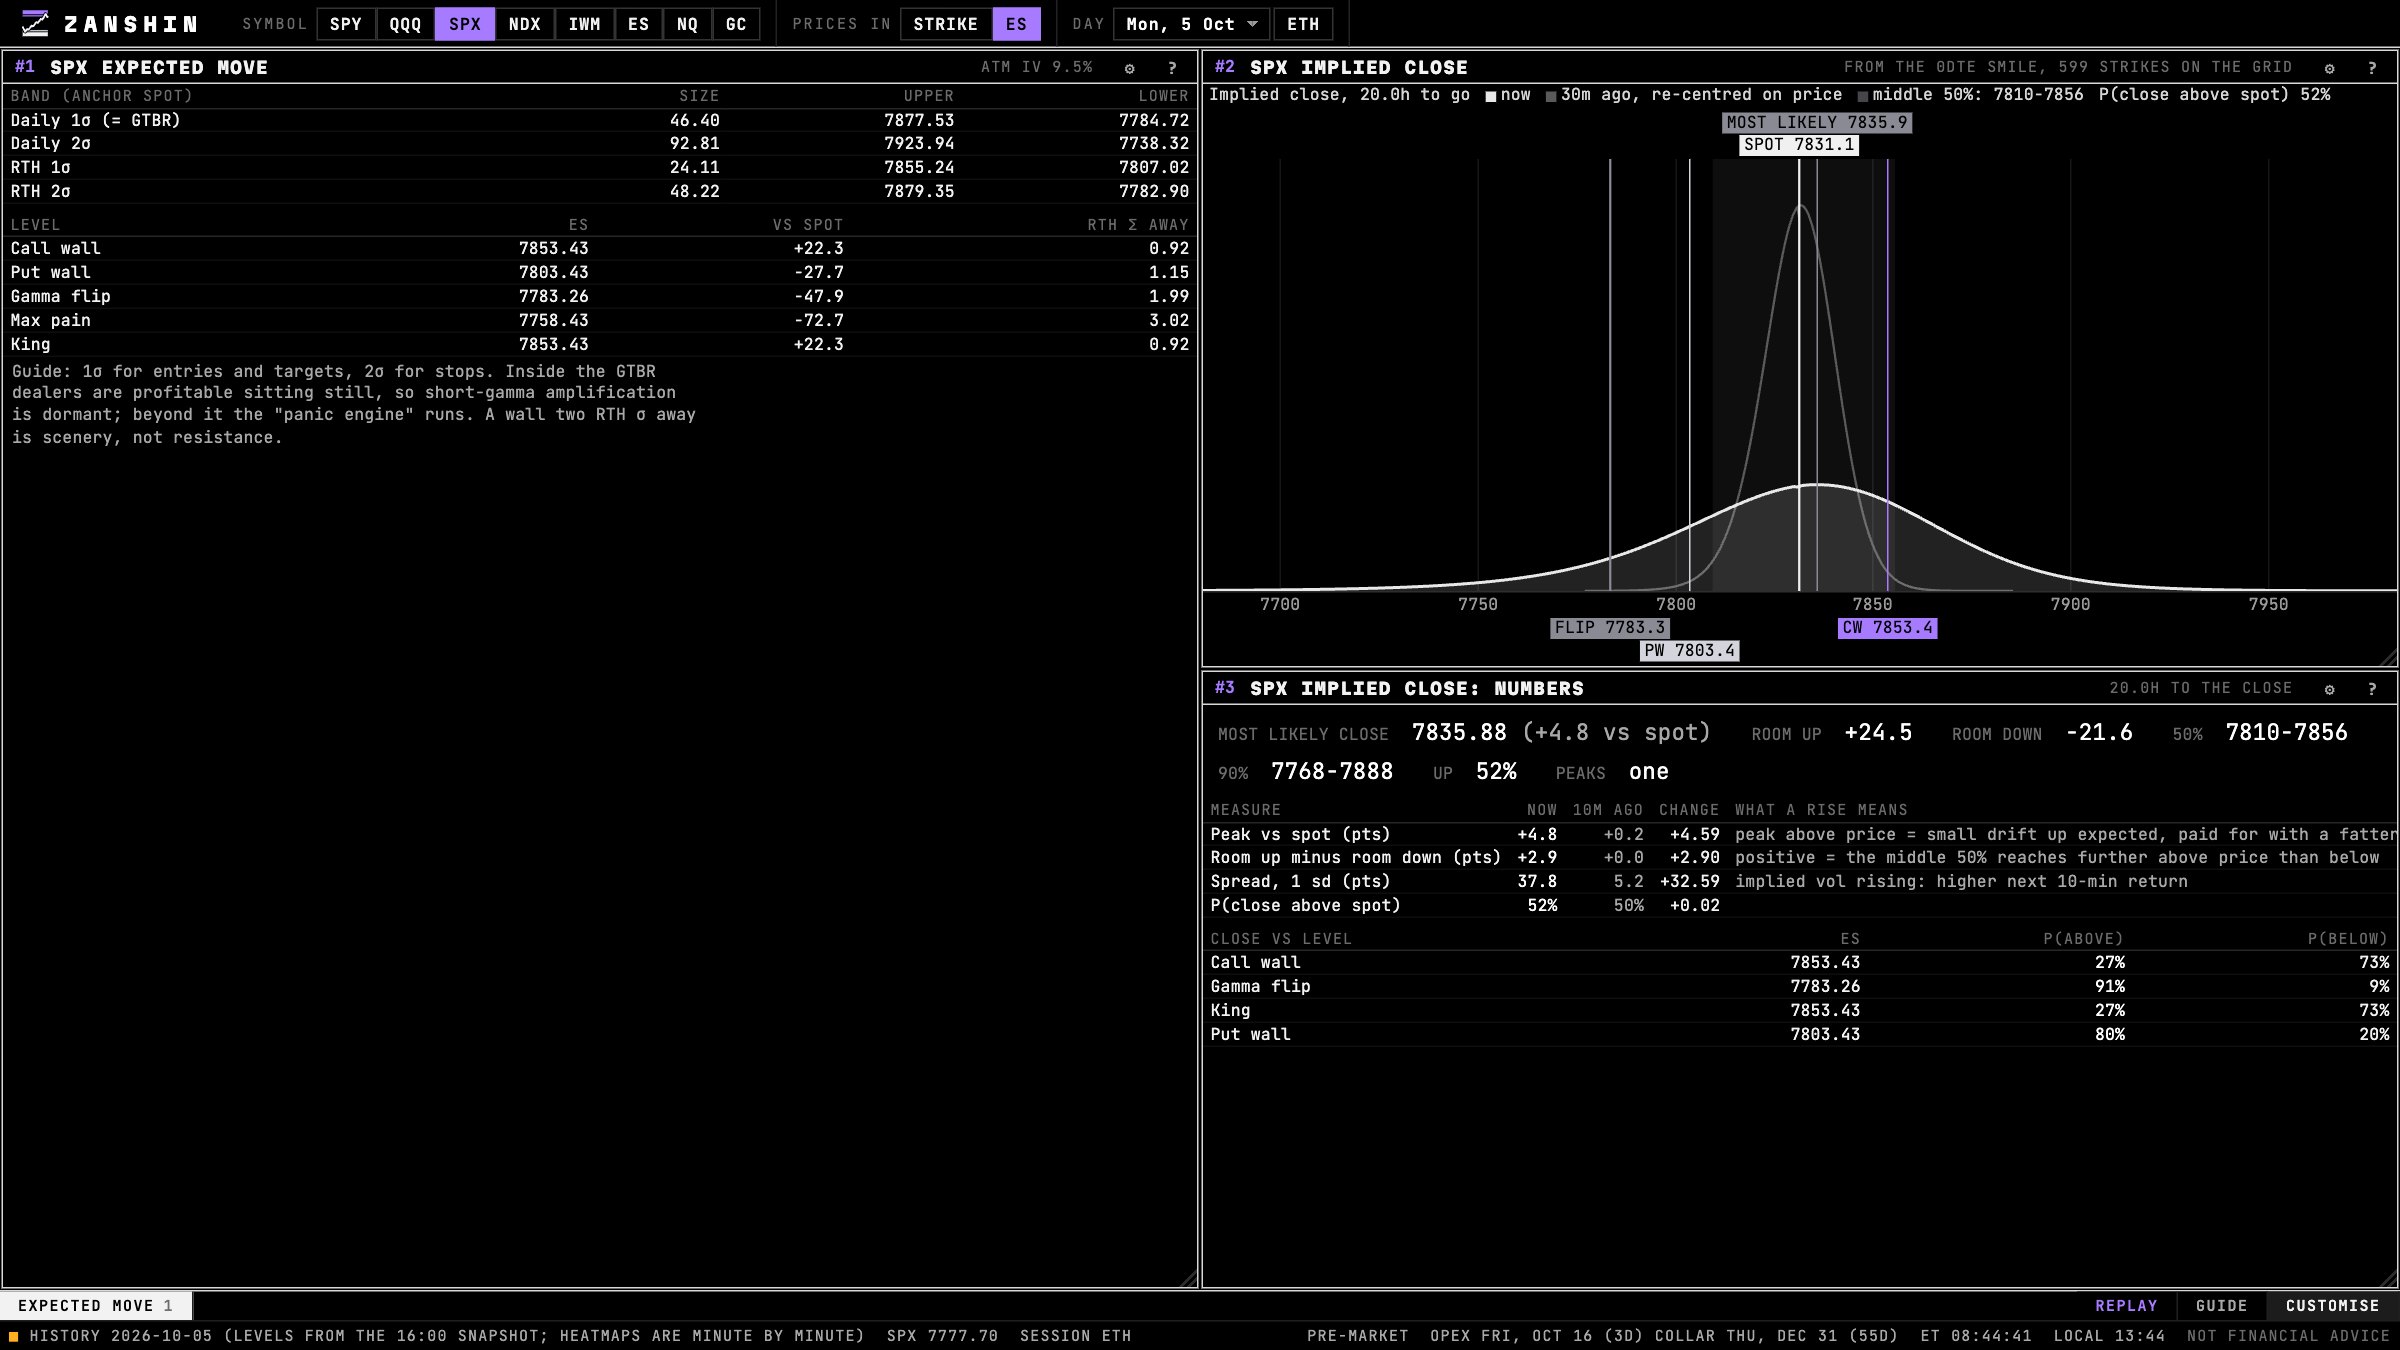
The expected move is the one-standard-deviation range the options market implies for a period: roughly spot × implied volatility × √time. About two times in three, a fair price finishes inside it.
The calculation
Expected move ≈ S × σ × √T
With σ the annualised implied volatility and T in years. An index at 7,000 with IV of 16%, over one trading day: 7,000 × 0.16 × √(1/252) ≈ 70.5 points, about 1%. A quick alternative is the price of the at-the-money straddle, which is close to 0.8 times the one-standard-deviation move.
Reading it
- 1σ: under a normal distribution, about 68% of outcomes fall inside.
- 2σ: about 95%.
- Real returns have fatter tails, so 2σ breaks happen more often than 5% of the time.
How fair were same-day implied moves?
We compared the at-the-money 0DTE implied move from 10:00, 12:00, 14:00 and 15:00 to the close against what happened, across seven sessions. Over the last two hours realised variance came in at about 0.89 times implied: same-day options priced slightly more movement than occurred. From 10:00 the ratio was swung by two volatile days. Roughly calibrated, slightly rich late in the day, and seven sessions is too few to call it more than that.
In Zanshin Flow
1σ and 2σ bands sit on the price chart, the Volatility page grades each level by how many sigmas away it is, and the Implied close pages turn the whole same-day chain into a probability curve for where the session closes.
Questions
How do you calculate the expected move?
What percentage of the time does price stay inside the expected move?
Are 0DTE options overpriced?
Not financial advice. This article explains how options and dealer hedging work. It is not a recommendation to buy or sell anything.