 ZANSHIN
Sign in
Dealer positioning
Gamma exposure (GEX): the dealer gamma book, in dollars
Gamma exposure is the estimated gamma market makers carry across an options chain, expressed as the dollars of hedging a 1% move in the underlying would force. It's the single number most dealer-positioning tools are built on.
The calculation
GEXstrike = Γ × open interest × contract multiplier × S² × 1%
That's the change in dealers' delta, in dollars, for a 1% move in the underlying. Sum it across strikes for a total, or keep it per strike for a map. The sign is the hard part: options data doesn't tell you who is long. The common convention assumes the public buys puts and sells calls, so dealer call gamma counts positive and put gamma negative. Zanshin Flow starts from open interest and adjusts each contract with the day's aggressor flow, and computes the open-interest-only figure alongside so the size of that assumption can be checked.
How to read it
- Positive GEX (long gamma): dealer hedging sells rallies and buys dips. Moves tend to be absorbed; ranges tend to be tighter.
- Negative GEX (short gamma): hedging buys rallies and sells dips. Moves get fed; ranges tend to widen.
- Per strike: the biggest concentrations become call and put walls; where the total changes sign is the gamma flip.
What it does and doesn't tell you
GEX describes the hedging pressure implied by the book right now. On our archive, negative-gamma half hours were much more volatile on some days and not on others, and once the last 30 minutes' realised volatility was known, the gamma regime added nothing to the next 30 minutes. It describes the volatility you're already seeing rather than forecasting more.
In Zanshin Flow
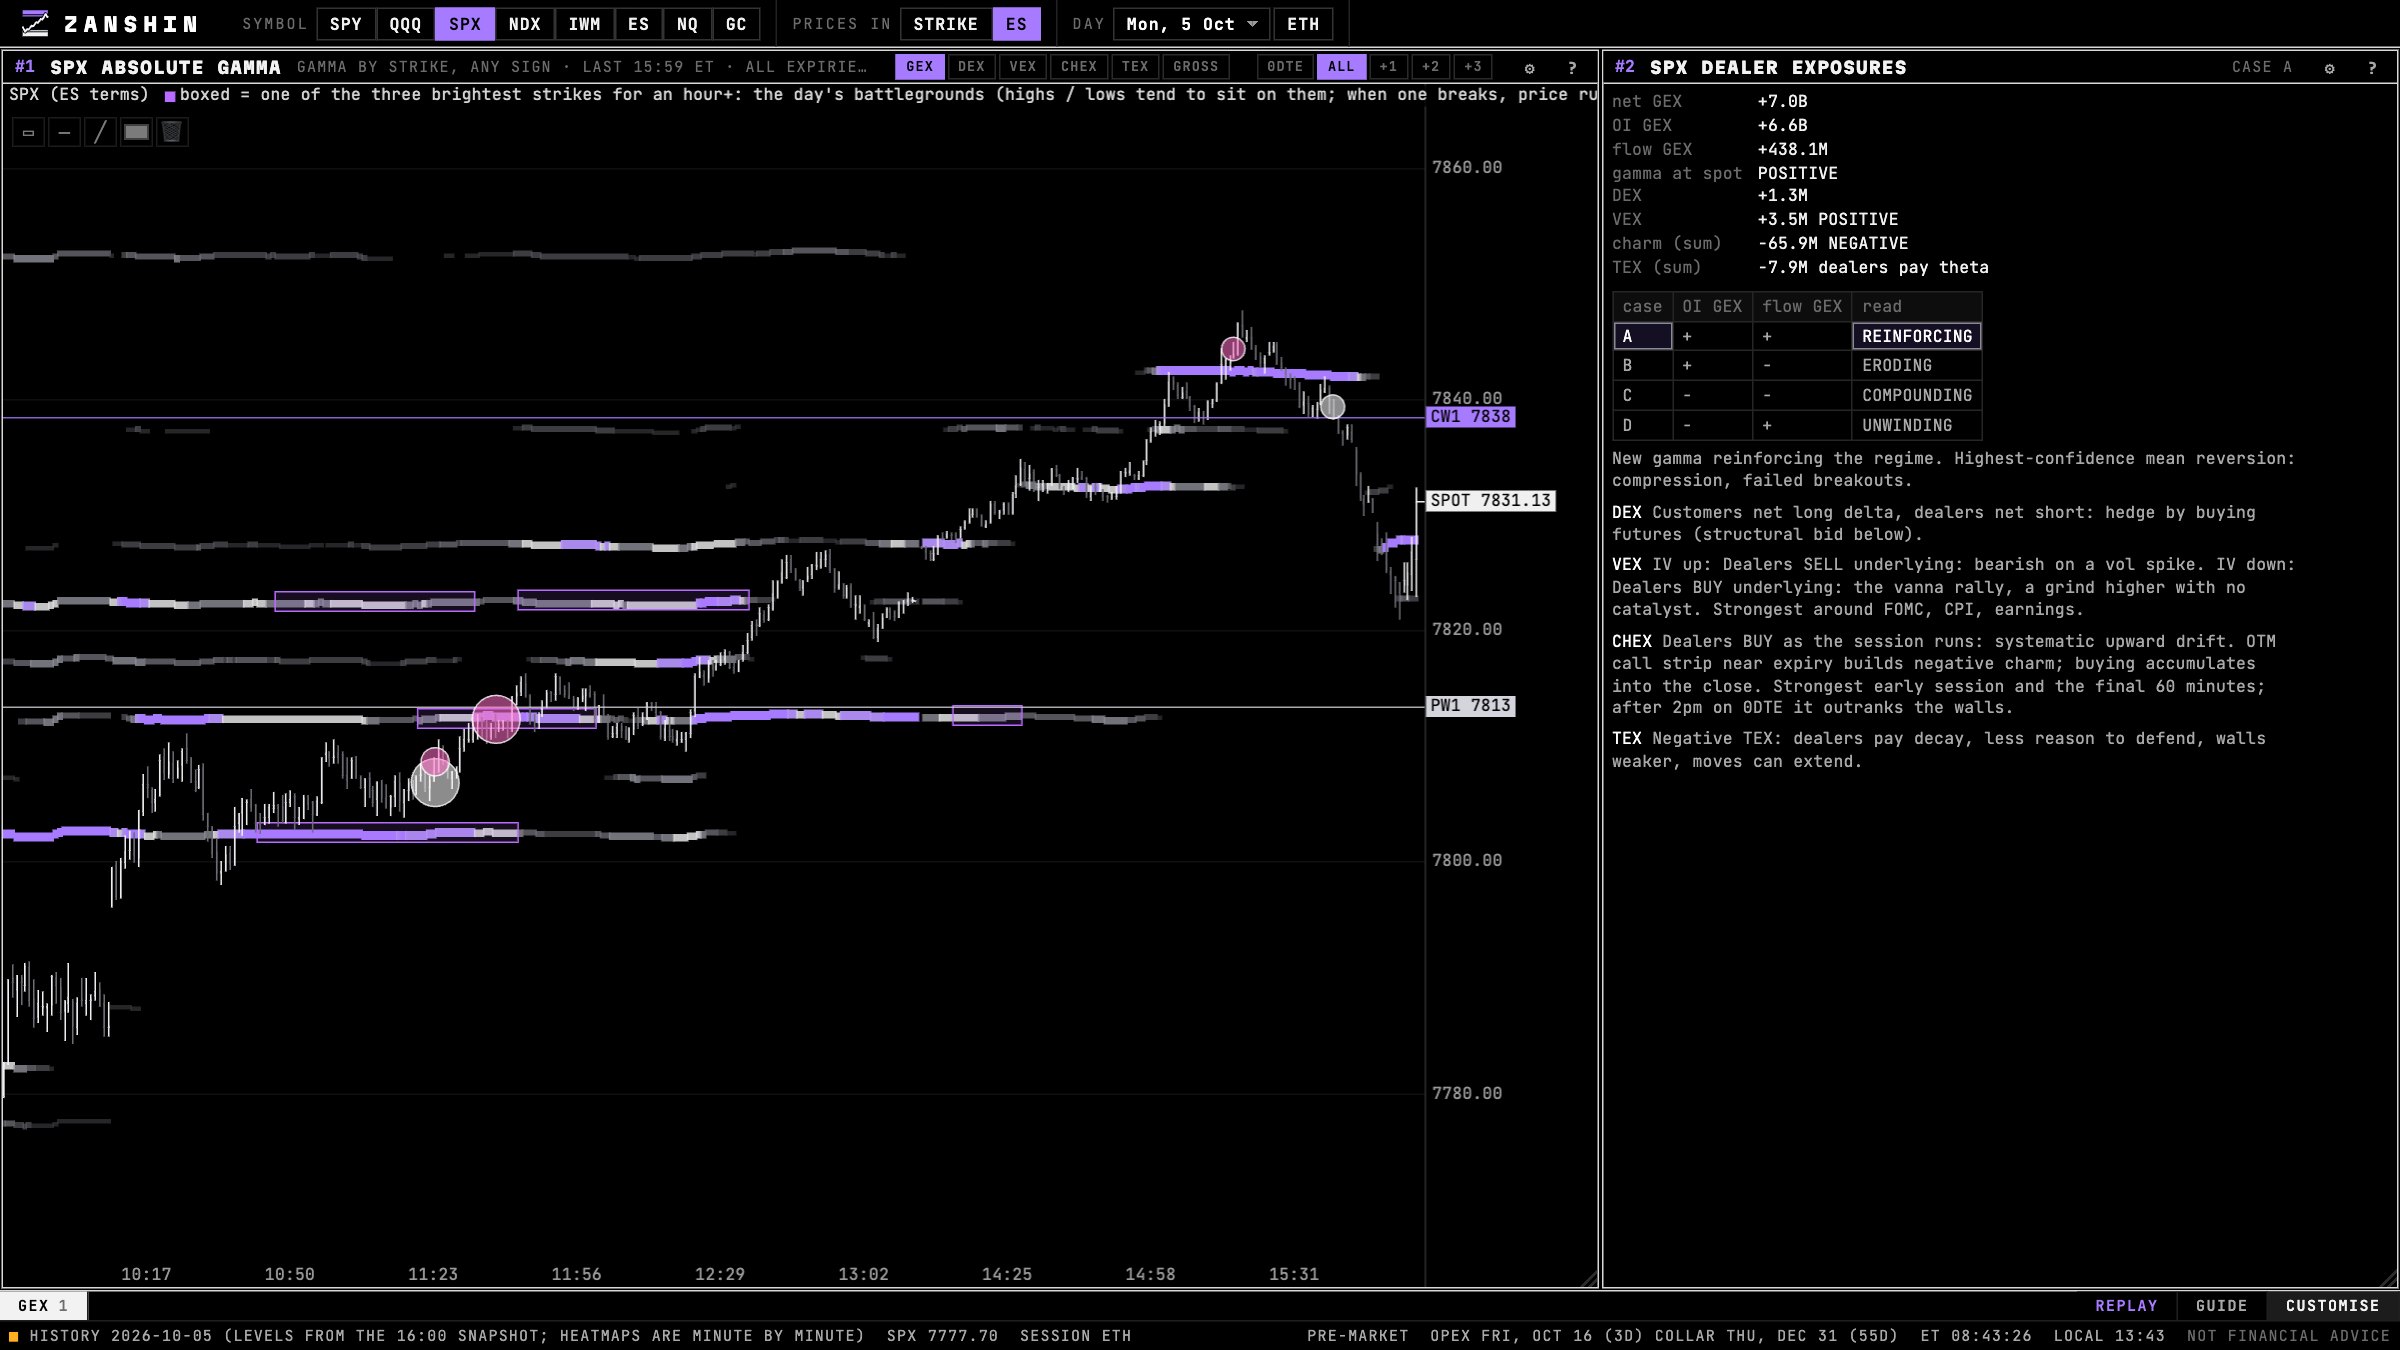
Spot over Gamma Field and Absolute Gamma draw GEX by strike under price, minute by minute, for SPX, ES, NDX, NQ, SPY, QQQ and IWM, with index strikes mapped onto ES and NQ futures prices. Any archived session can be replayed.
Questions
What does positive gamma exposure mean?
How is GEX calculated?
Is GEX accurate?
Not financial advice. This article explains how options and dealer hedging work. It is not a recommendation to buy or sell anything.